

Vola: Cash Advance & Credit
Vola inc.
- 4.6
- 2.05K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
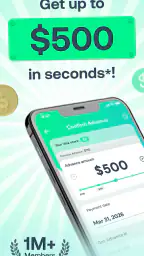
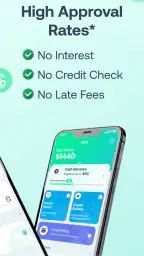
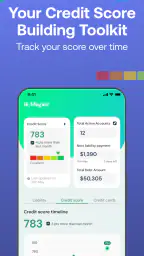
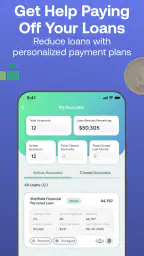
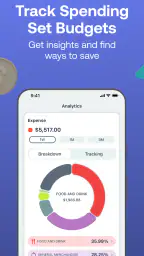
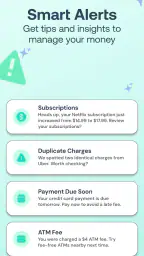
Vola: Cash Advance & Credit Pros and Cons
Pros
- Fast access to small cash advances when unexpected expenses arise.
- Simple mobile application process with minimal paperwork.
- May help bridge short-term gaps between paychecks.
- Credit-building features can support responsible financial habits.
- Clear repayment schedules help users plan upcoming payments.
Cons
- Advance limits may be low for larger emergency expenses.
- Fees or expedited-transfer charges can increase the borrowing cost.
- Repayment is often tied to your next paycheck, limiting flexibility.
- Eligibility may depend on income, banking history, and account activity.
- Late or failed repayments could lead to extra charges or account restrictions.
 Analysis by All-app
When an unexpected bill lands between paydays, the difficult part is often not finding a budgeting app; it is finding a tool that connects short-term cash pressure with a clearer view of everyday spending. Vola: Cash Advance & Credit is built for that particular situation. It is a free finance app from Vola inc. that combines access to an instant cash advance with budgeting and spending-tracking tools, while also presenting itself as an option for building credit without a traditional credit check.
I see it as a decision tool rather than a general-purpose banking replacement. The important question is not simply whether the app can help when money is tight. It is whether its combination of short-term assistance and financial organization matches the way you manage money. If you want one place to look at spending and explore an advance, it has a clear appeal. If your priority is long-term saving, detailed investing, or a conventional bank account, another type of app may serve you better.
What I would check before choosing Vola
My first decision criterion would be the reason I need the app. Someone facing a temporary gap before payday has a different need from someone trying to build a six-month emergency fund. Vola is aimed at the first person, while its budgeting and tracking features can help that person understand why the gap keeps appearing. That combination makes it more practical than an app that only displays account charts, but it also means the user has to be comfortable treating an advance as a short-term tool rather than extra income.
The second criterion is clarity. Before relying on any cash-advance service, I would read every screen related to eligibility, repayment, timing, and any optional charges presented during the process. A simple headline can make borrowing feel effortless, but the responsible decision depends on the complete terms shown in the app. I would also check how the amount fits into my next budget. If repaying an advance would immediately create another shortfall, the app is not solving the underlying problem.
The third criterion is whether I actually want credit-related guidance. Vola is not positioned only as a spending diary. Its store summary connects cash advances with credit building, budgeting, and spending tracking. That broader focus may be useful for someone who wants to improve financial habits while handling an immediate need. It may feel unnecessary, however, to a person who already has a reliable bank budget, a separate credit-monitoring service, and enough savings to cover irregular expenses.
I would also consider how much manual attention I am willing to give the app. Finance tools work best when I review transactions, notice recurring patterns, and act on what I see. No dashboard can fix a budget that I never revisit. Vola makes the most sense for someone prepared to use the tracking side after the urgent moment has passed, not just open it when money is short.
A realistic payday-gap example
Imagine that my car needs an unexpected repair a few days before payday. I could put the expense on a credit card, ask a friend, delay another payment, or investigate a cash advance. With Vola, I would first review my tracked spending and upcoming obligations, then decide whether the requested help is genuinely temporary. That order matters: looking at the budget before requesting money can prevent me from borrowing an amount that appears convenient but is difficult to repay.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
After payday, I would return to the spending view and look for the cause of the gap. Perhaps several small subscriptions, a higher grocery bill, or irregular transport costs have quietly pushed the monthly plan off course. The useful workflow is therefore two-part: use the advance only for the immediate disruption, then use the budgeting tools to reduce the chance of repeating it. If I used only the first part, I would be treating Vola as an emergency button rather than a finance app.
That is one of the less obvious strengths here. The same product can put the urgent decision and the follow-up review close together. It does not remove the need for judgment, but it can shorten the distance between borrowing and reflecting on the spending pattern behind the borrowing.
Where the app is especially convincing
The strongest part of Vola is the way its features address a connected problem. A cash advance handles timing, while spending tracking and budgeting address visibility. Those are not the same thing, but they often belong in the same conversation. Someone may have enough income overall yet still struggle because bills arrive before wages. Someone else may repeatedly face shortfalls because spending is not being monitored. Vola is relevant to both situations, although the second user needs to engage with the planning tools rather than depend on advances.
The credit-building angle is another reason some users may prefer it over a basic budgeting app. For a person trying to become more intentional about credit, having that goal alongside cash-flow management can make the app feel more focused. I would still avoid assuming that using any financial product automatically improves a credit profile. I would read the in-app explanations carefully and treat credit progress as something to understand and monitor, not a guaranteed result.
It is also approachable on paper for people who may be nervous about traditional credit checks. The store summary specifically presents the advance as requiring no credit check, which can make the app worth investigating for someone who has limited or damaged credit history. That does not mean every user receives the same outcome or amount, so I would regard the application process as an assessment rather than a promise.
The free price lowers the barrier to trying the budgeting side. That is useful because I can evaluate whether the spending view fits my routine without first committing to a paid finance subscription. Still, “free” should not replace careful attention to the terms of any advance or optional service. The cost of borrowing and the cost of using the app are separate questions, and I would keep them separate when making a decision.
Small workflows that make it more useful
My first practical tip would be to open the app during a calm week, not only during an emergency. That gives me time to understand the budget and tracking screens before I am under pressure. A rushed application can turn a financial decision into a reflex. Exploring the planning side first makes it easier to judge whether the app is genuinely helping.
My second tip would be to compare the requested advance with the full pay-cycle picture. I would list the bills due before the next income arrives, reserve money for essentials, and then consider whether repayment leaves enough room for food, transport, and other unavoidable costs. This is a more useful test than asking only, “Can I get the money?” The better question is, “What will my next week look like after repayment?”
My third tip would be to use spending tracking as a review tool after an advance, not as decoration. I would look for one change that could prevent another shortfall: moving a bill date where possible, reducing an avoidable recurring expense, or setting a small buffer. The goal is not to create a perfect budget overnight. It is to turn one emergency into information that improves the next cycle.
A further trade-off is worth noting. Combining borrowing and budgeting in one app can be convenient, but it may also make borrowing feel too close at hand. I would keep a personal rule: if the advance is needed for ordinary spending every cycle, I would stop and look for a different solution, such as negotiating bills, increasing savings gradually, or seeking independent financial advice. Convenience is valuable, but convenience should not hide a structural income problem.
How it compares with the usual alternatives
Compared with a standard budgeting app, Vola has a more immediate role when cash flow is the problem. A conventional budget can show that an expense is coming, but it cannot by itself address the timing gap. Vola may therefore feel more relevant during an emergency. The trade-off is that a pure budgeting tool may encourage more distance from borrowing, which can be healthier for someone who already tends to use advances repeatedly.
Compared with a bank’s built-in spending dashboard, Vola is more specifically focused on the combination of cash advances, credit goals, and budgeting. A bank app may be the better choice if I want all account activity, transfers, deposits, and everyday banking in one established place. Vola is more interesting when the bank’s spending view is too limited or when access to an advance is central to the decision.
Compared with a credit card, an advance may appear more targeted for a short gap, but the comparison should never stop at convenience. A credit card may offer familiar statements and a reusable payment method, while Vola’s appeal is its cash-flow and credit-oriented framing. The right option depends on the complete cost, repayment schedule, and my ability to avoid carrying the problem forward. I would not choose either simply because approval feels easier.
Compared with asking family or friends for help, an app can feel more private and structured. On the other hand, personal support may avoid some formal borrowing consequences, depending on the arrangement. That is a personal and sensitive choice, but Vola is most useful when I want a self-service route and can evaluate the repayment responsibly.
What may make switching worthwhile
Switching to Vola is not just a matter of installing another icon. I would need to spend time understanding the budget view, reviewing spending activity, and learning how the cash-advance process fits my pay cycle. If I already use a trusted budgeting system, the main cost may be duplication: two places to check, two sets of categories, and a greater chance that one view becomes outdated.
For that reason, I would start with a limited trial of the planning features rather than immediately making it the center of my finances. I would compare the app’s picture of my spending with my bank records and existing budget. If the information is easy for me to interpret and leads to a useful action, the switch has a practical reason. If it merely repeats figures I already understand, the borrowing feature would need to provide enough value to justify keeping another finance app.
There is also a behavioral cost. Moving from a bank dashboard to an app that includes advances can change how I respond to financial stress. I might become more likely to look for short-term access before considering a spending cut or payment arrangement. I would therefore decide in advance what qualifies as a genuine emergency and what does not. That simple boundary is more important than any attractive interface.
Users should also remember the age and platform context. Vola is rated for Everyone, and the app requires a minimum operating system of version 9. It is available as a free finance app, with current version 3.4.15, so I would check that my device meets the requirement before planning around it. The developer is Vola inc., and the app has been available since January 23, 2019, which gives it a meaningful history rather than making it a brand-new experiment.
Its audience size also suggests that it has reached beyond a tiny early-adopter group: the listing shows over 500 thousand installs, with an average rating of 4.6 from around 11 thousand ratings and roughly 2 thousand written reviews. I treat those figures as a sign of interest, not proof that the experience will suit me. Finance apps are highly personal; a feature that feels helpful to one person can feel restrictive or unnecessary to another.
Who should use it, and who should look elsewhere
I would recommend trying Vola if I regularly deal with short gaps between income and expenses, want to inspect spending in the same place, and am willing to make a repayment plan before requesting an advance. It may also suit someone who wants to learn more about credit while becoming more organized with day-to-day money. The best user is not simply someone who needs cash; it is someone who can use the cash-flow feature without abandoning the budgeting feature.
I would be cautious if my income is unpredictable, my essential costs already exceed my income, or I am relying on advances repeatedly. In those cases, the app may make a serious problem easier to postpone. A nonprofit counselor, a trusted bank adviser, a bill provider, or a broader debt-management approach could be more appropriate than another short-term financial tool.
I would also look elsewhere if I need detailed investment analysis, business accounting, extensive savings automation, or a full replacement for a bank. Vola’s identity is narrower and more practical: it connects immediate cash-flow support with budgeting, spending awareness, and credit-oriented goals. That focus is a benefit when it matches the need, but it is not a reason to expect every finance feature in one place.
My recommendation
My overall view is positive but deliberately measured. Vola offers a useful combination for people whose biggest financial difficulty is timing: money may arrive later than an important expense, and the user wants help understanding spending as well as handling the immediate pressure. The free entry point and no-credit-check positioning make it worth exploring for eligible users who feel excluded by traditional options.
I would recommend it as a structured short-term aid, not as a permanent answer to a recurring deficit. Before accepting an advance, I would read the full terms, calculate the next pay-cycle budget, and make sure repayment will not compromise essentials. Afterward, I would use the tracking and budgeting features to identify one concrete adjustment. That is where the app can become more than a quick fix.
If you already have stable savings and a strong budget, Vola may add little beyond features you already use. If you need a complete banking or investing platform, another category is a better match. But if you want cash-flow assistance alongside practical spending awareness, I think this app deserves a careful trial. Its real value depends less on getting money quickly and more on using that moment to regain control of the month.
Frequently Asked Questions
What is Vola: Cash Advance & Credit, and how does it work?
Vola: Cash Advance & Credit is a financial app designed to help eligible users access cash advances before their next payday, along with credit-building or financial-management features that may vary by user and location. After creating an account, you typically connect a qualifying bank account, review the available offer, and see the applicable fees, repayment date, and terms before accepting anything. Approval and advance amounts are not guaranteed.
Who can use Vola, and what information is required to apply?
Eligibility depends on factors such as your age, residence, income activity, banking history, and the availability of Vola’s services in your area. During registration, the app may request personal details, employment or income information, and permission to verify a bank account through a secure connection. You should provide accurate information and carefully review the privacy policy, data permissions, and eligibility requirements before completing the application.
How much money can I borrow through Vola, and when will I receive it?
The amount available through Vola is determined individually and can depend on your account activity, income patterns, repayment history, and other verification criteria. Delivery speed may also vary according to the selected transfer method, your bank, weekends, holidays, and whether an optional expedited service is offered. The app should display the advance amount, estimated arrival time, and any related cost before confirmation.
What fees, subscriptions, or repayment terms should I expect?
Before accepting an advance, check the complete cost breakdown rather than focusing only on the amount received. Depending on the product and your plan, Vola may involve membership charges, optional expedited-transfer fees, or other disclosed costs. Repayment is generally scheduled from a linked bank account on a specified date. Make sure you understand recurring charges, cancellation rules, and what happens if repayment fails.
Is Vola safe to use, and will using it affect my credit score?
Vola may use bank-connection and identity-verification services to evaluate eligibility and deliver its features, so users should review the permissions granted and the company’s privacy practices. Whether an advance or credit-related feature affects your credit report depends on the specific product and terms; not every cash advance is reported in the same way. Read the disclosures carefully, and avoid assuming that approval will improve your credit.


